


Medicare Part B premiums climbed to $202.90 a month in 2026. That’s $17.90 more than 2025, an increase of just under 10 percent.¹
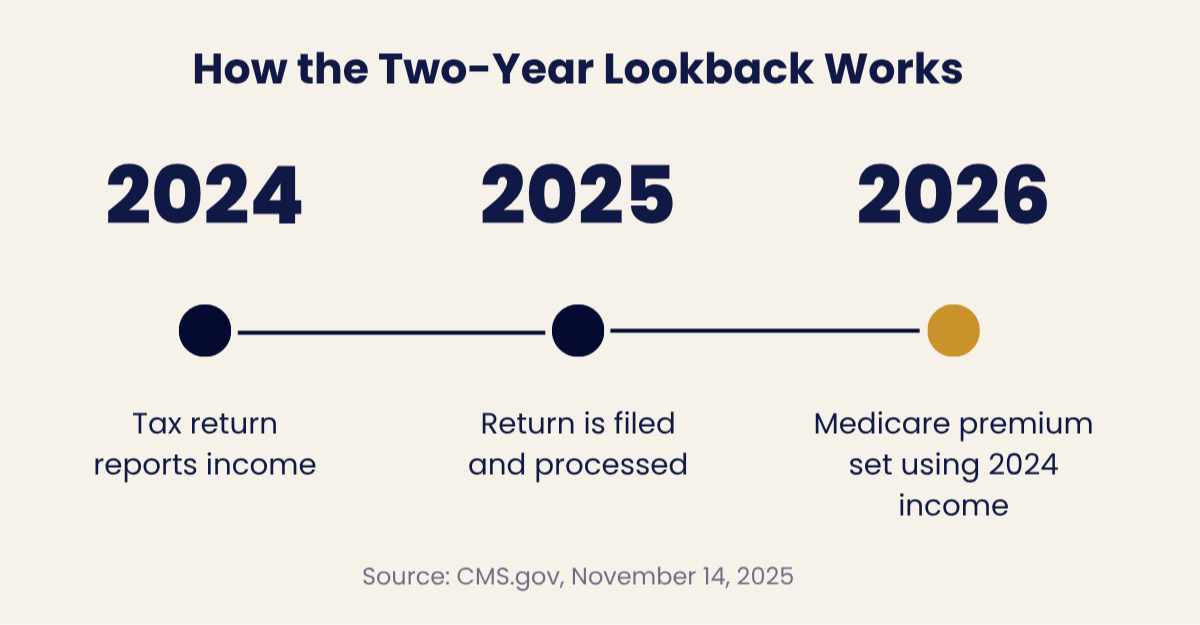
For higher earners, that’s only the opening act. On top of the standard premium sits a surcharge called the Income-Related Monthly Adjustment Amount, or IRMAA. And IRMAA has a quirk most people never see coming. It isn’t based on this year’s income. It’s based on your income from two years ago. That means a growing number of new retirees are paying a Medicare surcharge on a salary they no longer collect.¹
Why Is Your 2026 Medicare Premium Based on Your 2024 Tax Return?
Since IRMAA began in 2007, the surcharge has been set using the tax return filed two years earlier. So your 2026 premium is based on the modified adjusted gross income (MAGI) reported on your 2024 return. If that return isn’t available yet, Social Security falls back to 2023.²
The rule has been around for almost two decades. But most people meet it for the first time the year they enroll in Medicare.
How Much More Are Households Paying at Each Income Level in 2026?
If your MAGI from two years ago lands above certain thresholds, you pay the standard Part B premium plus an income-related adjustment on top.³
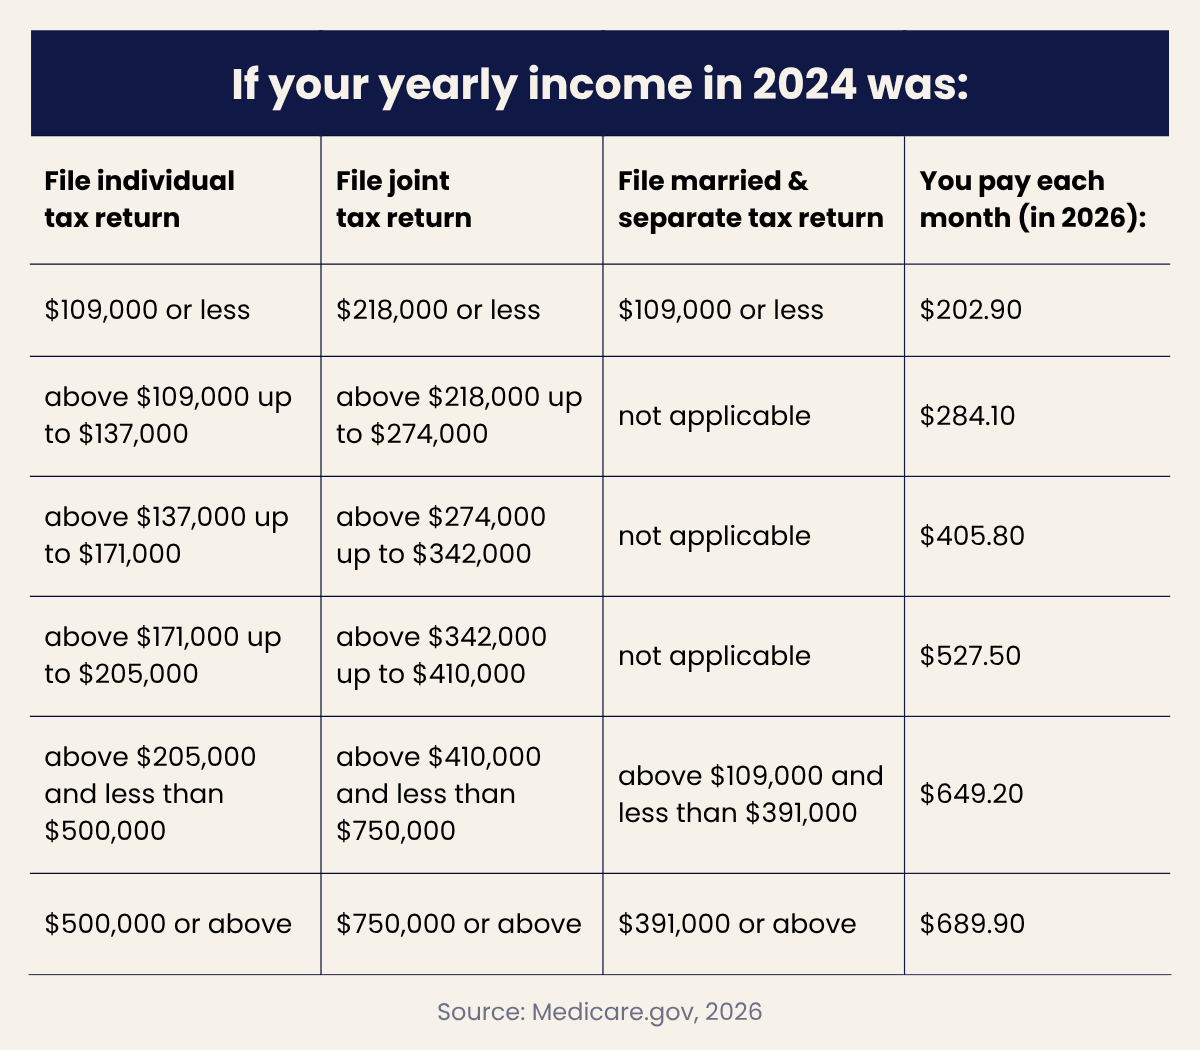
According to the Centers for Medicare & Medicaid Services, about 8 percent of people with Part B, and a similar share of those with Part D drug coverage, pay one of these surcharges. And it doesn’t take a giant income to get there. A pension combined with a required withdrawal from a retirement account can be enough to push a household past $109,000.¹
Why Can One Extra Dollar Trigger Thousands in Extra Premiums?
Because IRMAA is a cliff, not a slope.
Income tax brackets are marginal. Cross into a higher bracket, and only the income above the line gets taxed at the higher rate. IRMAA doesn’t work that way. Report one dollar over $109,000 as a single filer, and the surcharge for that entire tier applies for the full year, for both Part B and Part D.
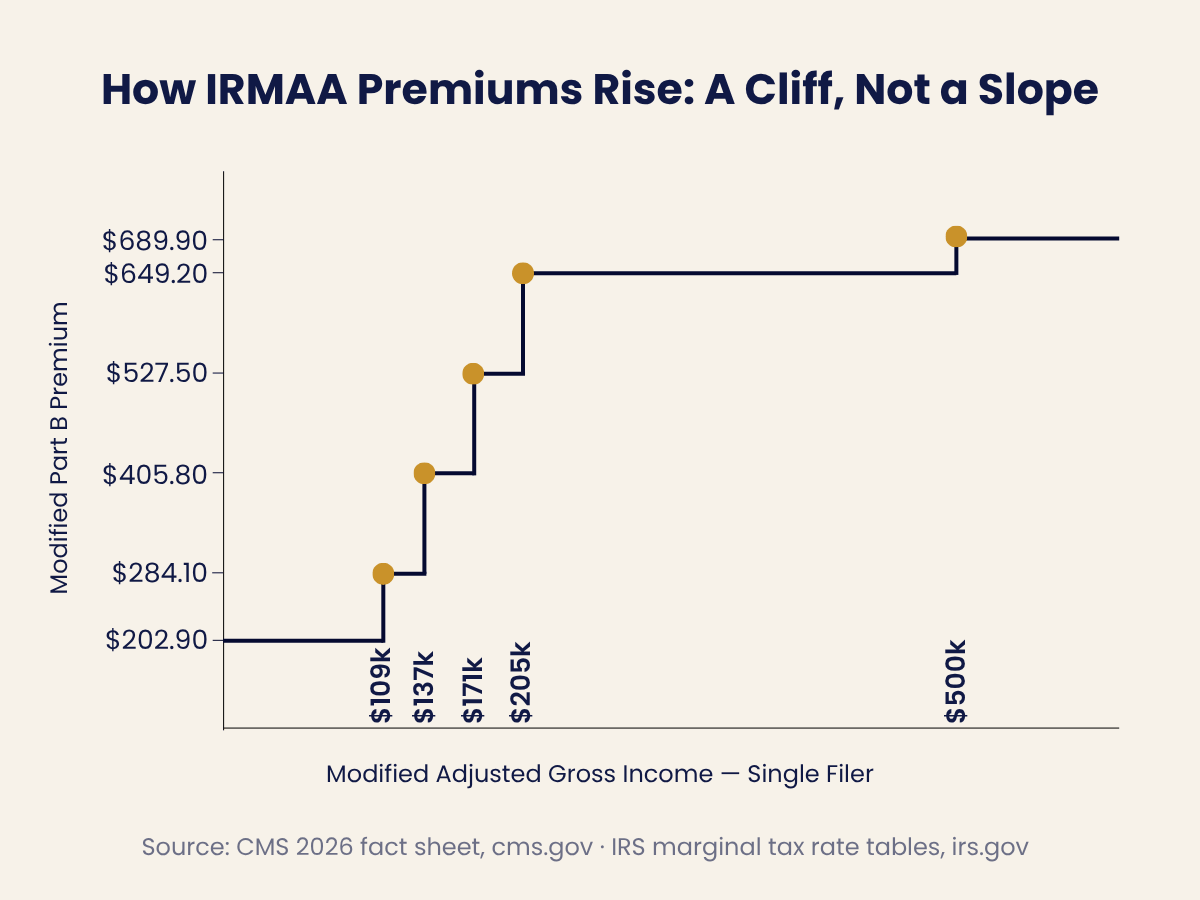
A single filer who reports $109,001 instead of $109,000 pays about $1,148 more for the year. For a married couple filing jointly, the same return sets both premiums, so both spouses get hit at once. That adds roughly $2,297 to their combined bill. For one dollar.³
The $500,000 single and $750,000 joint thresholds were set by the Bipartisan Budget Act of 2018. The lower brackets move up a little each year with the cost of living, but the top thresholds are expected to stay frozen until 2028.⁴
What Happens When Your Income Drops After That Tax Return Was Filed?
The two-year lookback assumes life stays fairly steady. Retirement rarely cooperates. Income often drops right in the same window that Medicare enrollment begins.²
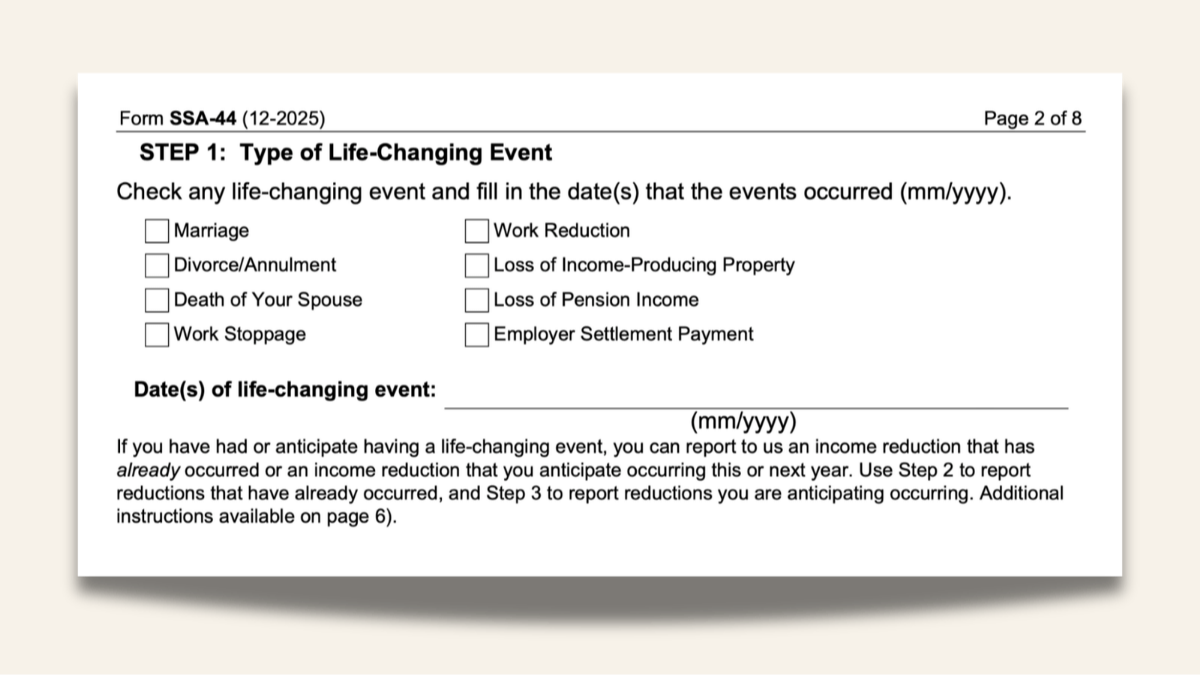
Social Security built a form for exactly this mismatch: Form SSA-44, Medicare Income-Related Monthly Adjustment Amount, Life-Changing Event. It lets you ask Social Security to base this year’s IRMAA on more recent income instead of a two-year-old tax return. But only if the drop was caused by one of eight recognized events:²
- Marriage
- Divorce or annulment
- Death of a spouse
- Work stoppage, which includes retirement
- Work reduction
- Loss of income-producing property (for example, a rental home) due to uncontrollable events like natural disasters
- Loss of pension income
- An employer settlement payment tied to a bankruptcy or reorganization
Every household’s situation is different, especially as Medicare age gets closer. If one of these events is in your recent past, or on the horizon, it’s worth a closer look. A surprise two years down the road is a lot easier to handle when you see it coming.
How Does Filing Form SSA-44 Work?
Social Security typically mails the initial IRMAA notice in late fall. It lists the income figure used and how to request a new determination. From that notice, you have 60 days to request a reconsideration, while a life-changing event can be reported at any time during the year through Form SSA-44. Processing generally takes several weeks, and premiums stay at the original, higher amount until a decision is made. If the request is approved, the difference is refunded or credited going forward.⁵
The form can be mailed, faxed, or dropped off in person at a local field office. Your tax, legal, or accounting professional may be able to help. But also consider working with your financial professional, who might be able to help you gather the information Social Security needs.²
Why Do So Few People File a Form That Could Save Them Thousands?
Part of it is structural. Medicare Part B premiums, including any IRMAA surcharge, are usually deducted from your Social Security benefit before it ever hits your account. That makes the cost close to invisible.⁶
The other part is psychological. When a number comes from a federal agency, it tends to feel permanent, even when that same agency built a formal process for changing it.
Out of sight. Out of mind. Out of pocket.
Final Thoughts: Don’t Let an Old Paycheck Set Your New Premium
IRMAA notices tend to land this time of year, right when a lot of new retirees are settling into Medicare for the first time. If your income has changed since that 2024 return, the number on your notice may not be the final word. As part of retirement income planning, we can model your projected MAGI, review whether a life-changing event applies, and potentially help you save some pretty significant money. Small timing decisions can make a big difference.
If you, or someone you know, is new to Medicare and paying a surcharge based on an old paycheck, give us a call.
We are proud to be your financial friend. And clarity starts with a simple conversation.
1 CMS.gov, November 14, 2025.
2 SSA.gov, 2026.
3 Medicare.gov, 2026.
4 TheFinanceBuff.com, August 22, 2026.
5 Medicare.gov, 2026.
6 AARP.org, December 27, 2025.